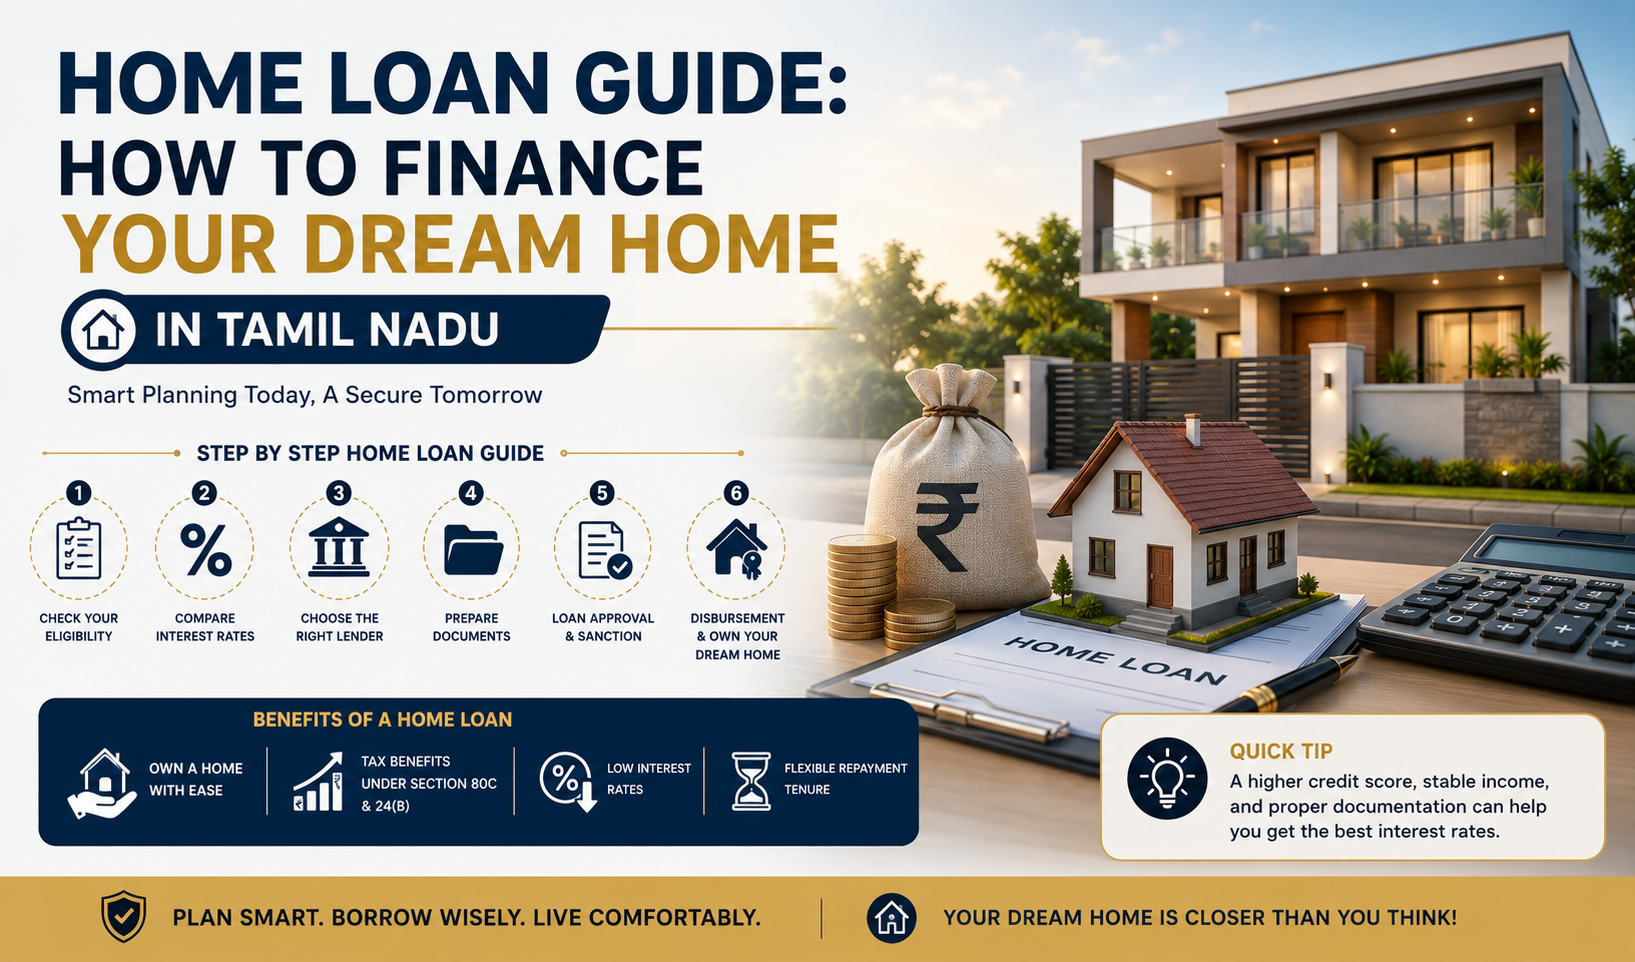
Planning to buy your dream home in Nagercoil or Kanyakumari District? Learn how home loans work in Tamil Nadu, from eligibility and down payments to interest rates, required documents, EMI planning, and choosing the right financing option for your new home.
Financing is one of the most important — and often most misunderstood — parts of buying a house for sale in Nagercoil. The right home loan can make your purchase more manageable, while the wrong financing decision can increase your long-term cost significantly.
Whether you are buying a family home in Nagercoil or investing in a premium property elsewhere in Kanyakumari District, it is important to compare lenders, understand your eligibility, calculate the total upfront cost, and review all tax and registration obligations before signing the agreement.
Compare Banks and Housing Finance Companies
Many buyers begin their home loan search with established banks and financial institutions. Depending on your eligibility and the property, options may include public sector banks, private sector banks, and housing finance companies.
Each lender can differ in areas such as:
- Home loan interest rate
- Loan eligibility
- Loan-to-value ratio
- Required down payment
- Processing fees
- Legal and technical verification
- Property valuation
- Disbursement process
- Prepayment conditions
- Loan tenure
Do not choose a lender based only on the advertised interest rate. The total cost of borrowing and the lender’s property approval process are equally important.
Understand How Much a Lender Will Finance
If you are buying a luxury house for sale in Nagercoil, the lender may not finance the entire purchase price. The approved loan amount can depend on your income, credit profile, repayment capacity, property valuation, applicable loan-to-value limits, and the lender’s internal policies.
For example, if a property costs ₹1 crore and you are seeking a home loan of ₹80 lakh, do not assume that approval is automatic. The lender will generally review both the borrower and the property before confirming the final eligible amount.
Budget for More Than the Down Payment
One of the most common mistakes home buyers make is planning only for the down payment. In reality, the upfront cost of purchasing a home can include several additional expenses.
Depending on the transaction, buyers may need to budget for:
- Down payment
- Applicable stamp duty
- Registration charges
- Home loan processing fees
- Legal verification charges
- Property valuation charges
- Applicable TDS compliance
- Insurance-related costs
- Other statutory or professional expenses
These expenses can add a meaningful amount to the total cost of buying a home in Nagercoil or Kanyakumari District, so they should be calculated before finalizing your budget.
Understand TDS on High-Value Property Transactions
Buyers purchasing higher-value immovable property should understand the applicable TDS requirements under Indian income-tax law.
Where the legal conditions and threshold under Section 194-IA are met, the buyer may be required to deduct TDS and deposit it with the government within the prescribed process and timeline.
Because tax rules can change and the applicable amount may depend on the transaction structure, sale consideration, stamp duty value, seller status, and other factors, buyers should confirm the current requirement with a qualified Chartered Accountant or tax professional before completing the purchase.
Do Not Understate the Property Value to Reduce Costs
Buyers should be cautious about any suggestion to record an artificially lower property value solely to reduce stamp duty, registration expenses, or tax obligations.
The value stated in property documents should comply with applicable law, government valuation requirements, lender conditions, and tax rules. An incorrect or artificially understated value may create future complications involving:
- Tax compliance
- Property registration
- Loan processing
- Future resale
- Capital gains calculations
- Legal disputes
Always seek independent legal and tax advice before entering into any arrangement involving different agreement values, registration values, or payment structures.
How to Compare Home Loan Options
Before finalizing financing for a house for sale in Nagercoil, compare multiple lenders using the same loan amount and tenure.
Ask each lender clearly about:
- Current interest rate offered to you
- Fixed or floating interest structure
- Maximum eligible loan amount
- Required own contribution
- Expected monthly EMI
- Total interest over the loan tenure
- Processing and administrative charges
- Property valuation process
- Legal verification requirements
- Disbursement conditions
- Part-payment options
- Foreclosure conditions
Check the Property Before Applying for the Loan
A strong income and good credit score do not automatically guarantee a home loan. The property itself may also need to satisfy the lender’s legal and technical requirements.
Before applying, verify important documents such as:
- Title and ownership documents
- Encumbrance Certificate
- Patta and relevant land records
- Layout approval documents
- Building plan approval
- Property tax records
- Sale agreement
- RERA details, where applicable
For buyers considering a new home in Nagercoil, properly documented and approved properties can generally make the legal verification process more straightforward.
Plan Your EMI Around Real Life
The maximum loan amount offered by a lender is not always the right amount to borrow. Your EMI should leave enough room for everyday family expenses, education, healthcare, emergencies, insurance, savings, and future financial goals.
Before choosing a loan, ask yourself whether the EMI would still be manageable if:
- Interest rates increase
- Your monthly expenses rise
- You face a temporary income disruption
- Unexpected family expenses occur
A sustainable home loan is one that helps you own your dream home without placing unnecessary pressure on your long-term finances.
What This Means for Home Buyers in Nagercoil
If you are planning to buy a home in Nagercoil or Kanyakumari District, compare multiple financing options before making a commitment. Look beyond the interest rate and understand the complete transaction cost.
The right approach is simple: compare lenders, verify the property, understand your tax obligations, budget for registration and other expenses, and choose an EMI that remains comfortable for your family.
Looking for a House for Sale in Nagercoil?
Mercury Developers builds new luxury homes across Nagercoil and Kanyakumari District, with a focus on approved developments, quality construction, modern design, and comfortable living.
Call: 9566 9566 23
Your Dream Home, Our Responsibility.
Share this article
Looking for a Property?
Talk to Our Experts
Get free advice on buying or renting land, houses, or commercial properties in Nagercoil.
Chat on WhatsApp +91 919566956623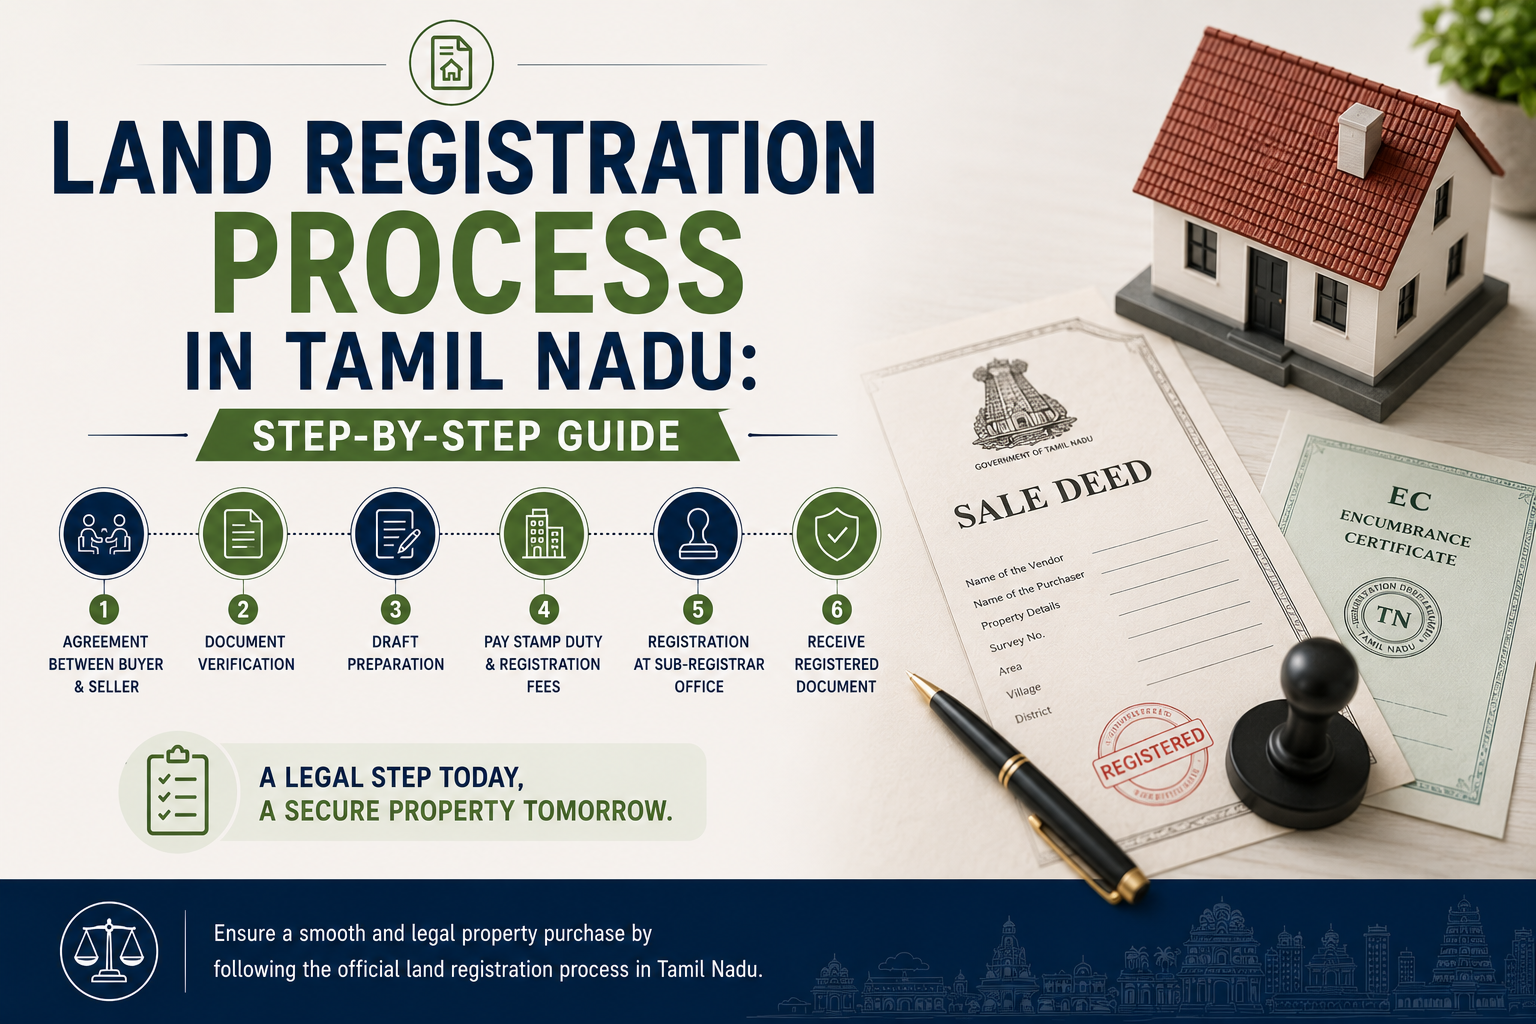
Properties
Browse Our Listings
Find land, houses and commercial properties in Nagercoil & Kanyakumari District.
House for Sale in Nagercoil Land for Sale in NagercoilKeep Reading